All Categories
Featured
The Comprehensive Guide to Regional Market Success for 2026
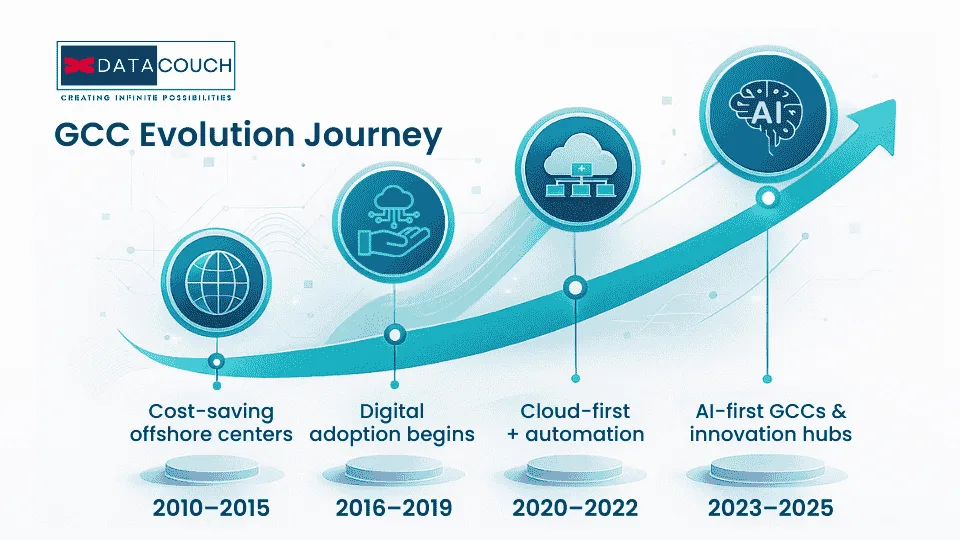
Maximizing Corporate Efficiency Through Operational Excel...
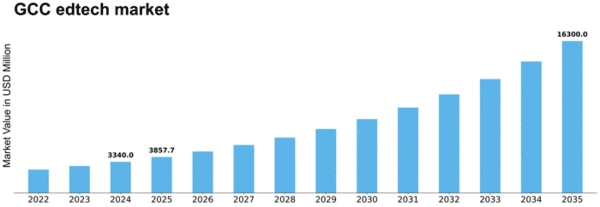
Industrial Excellence: a Strategic Pillar for Regional Growth
Rather than marking a cyclical rebound, 2026 is progressively viewed as a combination year, in which diversification-led development becomes more deeply embedded in the area's economic model, reducing reliance on hydrocarbons and increasing durability to external shocks. Forecasts from significant institutions broadly converge on a more powerful GCC development profile in 2026 than in 2025, supported by durable domestic need, continued non-oil expansion, and (to differing degrees) a firmer hydrocarbon contribution.
3.2 percent growth in 2025, accelerating to 4.5 percent in 2026. Sees momentum improving, with GCC output development projected to rise from 1.7 percent in 2024 to 3.3 percent on average in 2025, showing a shift toward more positive overall conditions.
Driving Strategic Excellence in the GCCThe IMF's World Economic Outlook (October 2025) projects international growth reducing to 3.1 percent in 2026, with advanced economies around 1.5 percent and emerging market and developing economies just above 4 percent. On that contrast, a 4.44.5 percent GCC growth would place the region materially ahead of the world average and slightly above (or broadly in line with) the emerging-market aggregate, enhancing the GCC's status as a fairly high-growth pocketprovided that regional danger conditions stay contained and reform momentum holds.
Driving Strategic Excellence in the GCCInformation from the GCC Statistical Center show that non-oil sectors already account for more than 73 percent of overall GDP, a share that has actually continued to increase as federal governments broaden financial investment in services, infrastructure, and innovation. According to Oxford Economics, non-energy activity across the GCC is projected to grow by around 4.1 percent in 2026, supported by strong labor markets, enhancing credit conditions, and increasing investment in innovation and AI-related infrastructure.
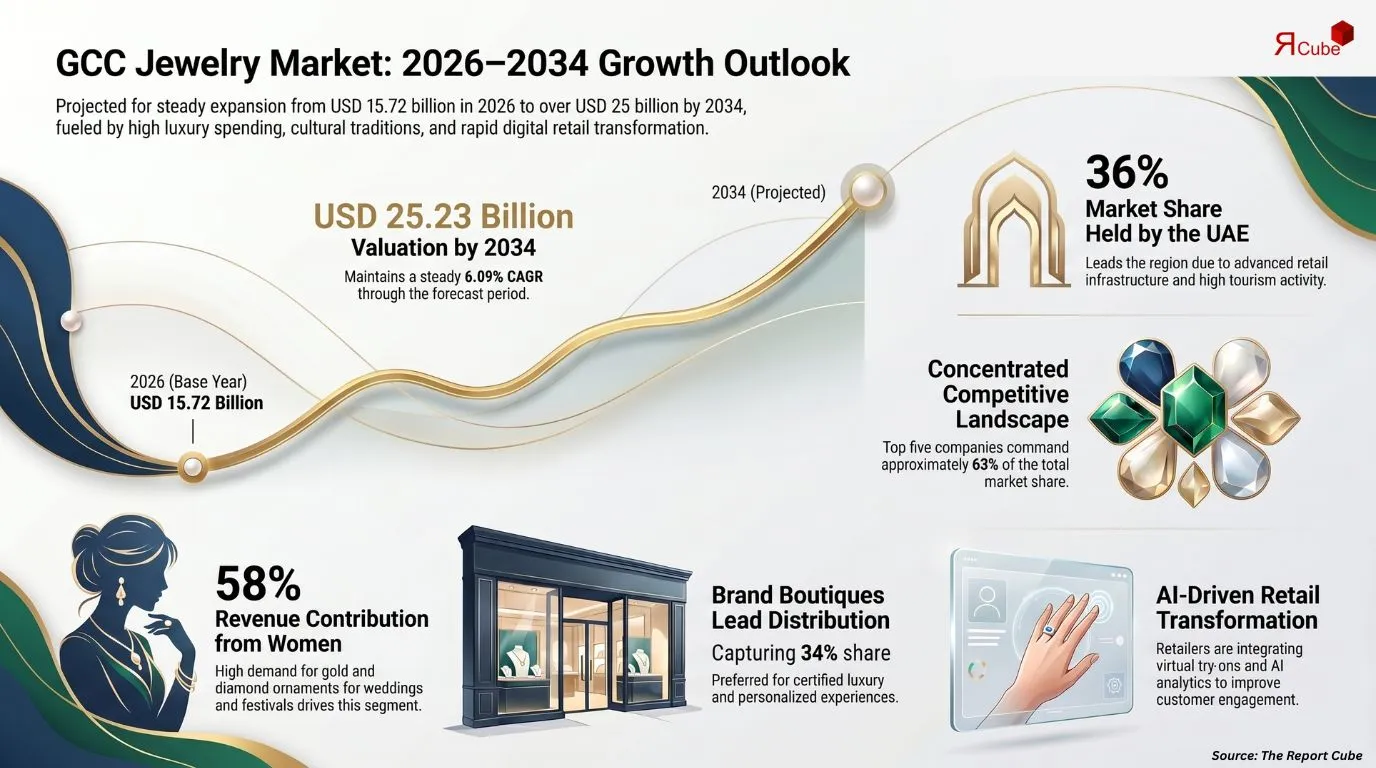
Analysing New Market Data for Strategic Growth
Public-sector investment and reform stay central to sustaining this pattern. Policy steps intended at attracting foreign direct investment, relieving foreign ownership guidelines, expanding capital markets, and supporting private-sector participation continue to underpin non-oil growth and reduce the area's exposure to oil cost volatility. While hydrocarbons no longer dominate the development outlook, oil incomes are expected to play a supportive function in 2026.
Oxford Economics expects Brent crude costs to fall below USD 60 per barrel in early 2026, restricting the near-term contribution of oil extraction to GDP. Oil supply is forecast to increase again in the 2nd half of the year, with a full loosening up of remaining production caps most likely by mid-2027.
Macroeconomic conditions across the GCC stay broadly supportive of growth. Inflation is anticipated to remain low, with the IMF forecasting typical inflation of 2 percent throughout the region in 2026. Stable costs are helping maintain genuine home incomes and underpin customer spending, which Oxford Economics expects to grow by approximately 3.5 percent over 20262027.

Latest Posts
The Comprehensive Guide to Regional Market Success for 2026

Driving Regional Industrial Expansion through Strategy
Evaluating Legacy Models and Future Business Frameworks